Employment, inflation, and retail sales set the tone for a week marked by volatility and sector rotation on Wall Street.
In the latest episode of the Mercado Sobre Ruedas podcast, financial markets journalist Julián Yosovitch analyzes employment, inflation, and the growing volatility in the U.S. market, as well as the performance of the American economy in a context where unemployment is falling but uncertainty remains. Below, we review Yosovitch’s main insights.
The week began with a batch of U.S. macroeconomic data that had been delayed due to the partial government shutdown that ended on February 3. These releases reshaped market expectations regarding the direction of Federal Reserve monetary policy. Employment, inflation, and retail sales drove a week characterized by volatility and sector rotation on Wall Street.
Strong employment creation and rate uncertainty
The most relevant data point was from the labor market. In January, nonfarm payrolls increased by 130,000 jobs, well above the 55,000 expected by analysts surveyed by Dow Jones and also higher than the 48,000 recorded in December.
The unemployment rate fell to 4.3%, compared to the 4.4% forecast, marking the best monthly reading since December 2024. This comes in a context where average job creation over the past year had barely reached 15,000 jobs per month. Meanwhile, average hourly earnings rose 0.4% month-over-month and 3.7% year-over-year, in line with expectations.p
Moderate inflation brings relief
On February 13, a data release partially eased market concerns, Yosovitch notes. January’s Consumer Price Index (CPI) came in at 2.4% year-over-year, slowing compared to the previous month. Core inflation, which excludes volatile prices, held steady at 2.5%.
This figure was key because, according to Yosovitch, had it shown acceleration, it would have reignited the risk of a stagflation scenario (economic weakness combined with rising inflation), limiting the Federal Reserve’s room to maneuver. With inflation under control, the market once again began to price in potential rate cuts later in the year.
Current implied probabilities suggest the following path for the Fed:
- 92% chance the Fed keeps rates unchanged in March (3.50%–3.75% range)
- No change in April
- First 25-basis-point cut in June (51% probability)
- Second cut in September
- Possible fourth and final cut in March 2027, bringing rates toward the 2.75%–3% range
Despite the positive January reading, the labor market still shows structural fragility, one of the main arguments from Fed members who support monetary easing.
More volatility and sector rotation
To conclude his analysis, Yosovitch notes that monetary uncertainty was reflected in the CBOE Volatility Index (VIX), which reached 21 points during the week.
In equities, the technology sector fell 0.8% for the week and the S&P 500 declined 1%. In contrast, there has been a rotation toward sectors more closely tied to the real economy, such as:
- Energy: +21% year-to-date
- Mining: +20%
- Materials: +17%
- Oil and Gas: +17%
- Consumer Staples: +15%
- Industrials: +12%
By contrast, long-duration technology stocks are down 8% year-to-date; the financial sector is down 5%, and traditional technology is off 2.7%.
The market appears to be shifting away from growth stocks, which led the rally over the past three years with double-digit annual gains, toward value and cyclical sectors more closely linked to macroeconomic performance.
Despite recent corrections, major indexes remain near historic highs. The Dow Jones Industrial Average even reached 50,000 points, setting a new record.
The combination of resilient employment, contained inflation, and weakening consumption leaves the Federal Reserve at a crossroads: proceed cautiously or begin a rate-cutting cycle to sustain growth.

Being a Parent From the Cab: The Other Life of a Truck Driver
Behind every truck driver, there is also a story that rarely appears on navigation maps: being a parent on the road.

Diesel Prices Hit Record High in the U.S. Prompting HOS exemption
The price of diesel reached a new record averaging nearly $6.45 per gallon in the United States.
$2.52 Billion I-10 Project Will Transform a Major U.S. Freight Corridor
A $2.52 billion federal loan will help expand I-10 in Alabama, one of the nation’s major freight corridors. The project aims to eliminate Mobile’s long-standing bottleneck, cut travel times by up to 30 minutes, and improve truck access to the Port of Mobile.
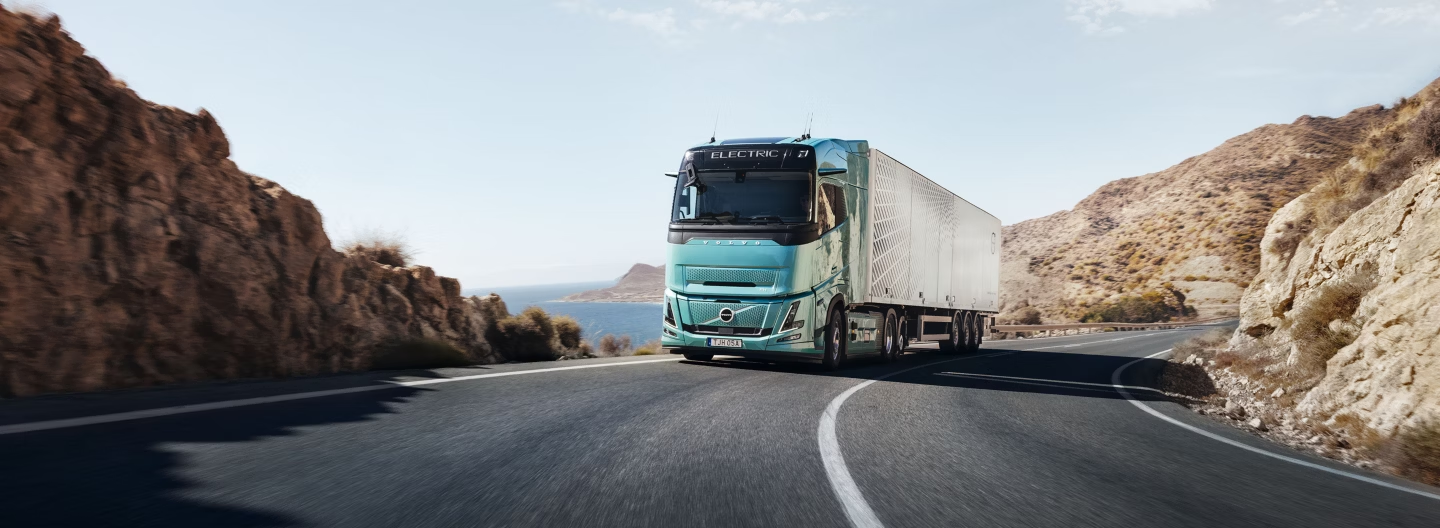
Inside Volvo’s 2027 Truck of the Year Lineup
Volvo Trucks has pushed its new electric generation to as much as 435 miles of range, with increased payload capacity and faster charging. Here’s a closer look at the lineup that just earned one of the trucking industry’s biggest awards.
What Is a Department of Transportation (DOT) Background Check?
Here’s what truck drivers need to know about DOT background checks.
South Florida Diesel Prices Rise More Than 70%, Impacting Trucking Industry
Trucking operations in South Florida have come under pressure following the recent increase in diesel prices.